 Payment Institution
Obtained Nexpay’s FCA Authorised Payment Institution licence.
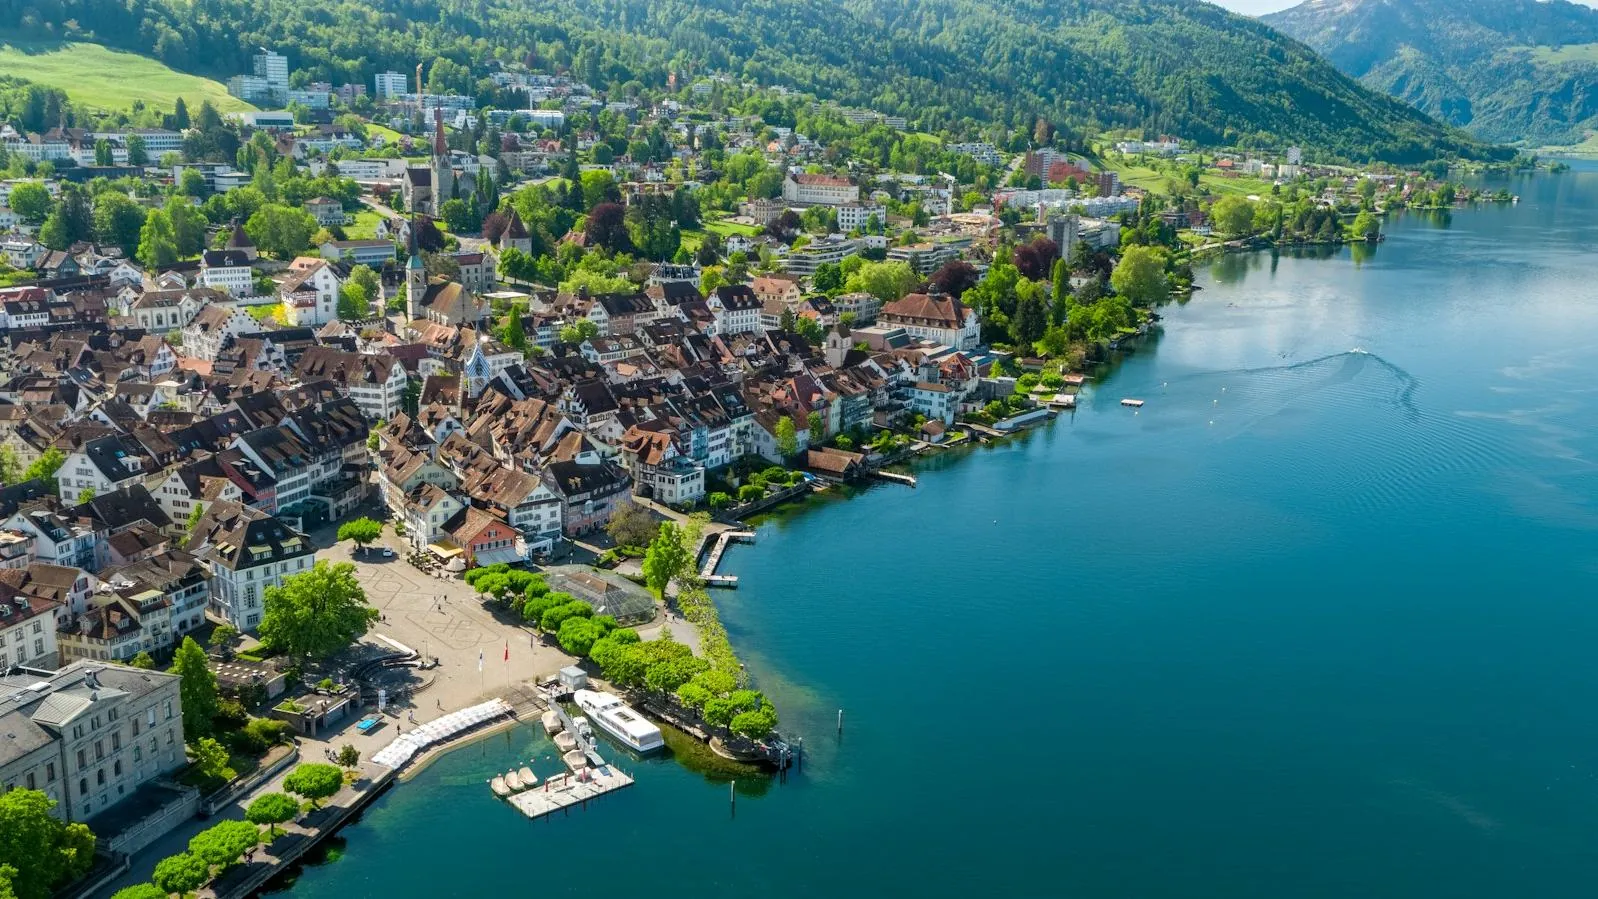
Crypto exchanges, custodians and trading venues build in Switzerland on an established framework centred on Zug and Zurich, where the activity sets which of three routes applies.
Selected engagements from more than 250 licences obtained since 2013, for payment, e-money, cryptoasset and consumer credit firms.
 Volkswagen



 Payment Institution
Obtained Nexpay’s FCA Authorised Payment Institution licence.
 Electronic Money Institution
Obtained Dzing Finance’s FCA Authorised Electronic Money Institution licence.
Obtained Orbital’s FCA Authorised Payment Institution licence.
Our realistic timeline from submission, set against the regulator’s own published figures.
Safeguarding, operating and settlement accounts opened alongside the application, so you trade on authorisation.
Candidates introduced for the board and senior managers, each assessed against the regulator’s standard.
A reply within three business hours and a written proposal the same day: the licence, the requirements, the cost and the timing.
You will need board members and senior managers who each provide ID, a CV, references and criminal record and debt extracts under six months old.
One engagement and one timetable, from scoping to launch. Speak to an expert about the people, the banking and the technology for this licence.
The regulator’s requirements, capital, timing, fees and the questions firms ask, from the regulator’s own publications.
A firm that exchanges, brokers, holds or trades crypto-based assets from Switzerland sits under one or more of FINMA’s existing regimes rather than a single crypto licence. An exchange or broker is a financial intermediary under the Anti-Money Laundering Act and joins a recognised self-regulatory organisation for AML supervision. A custodian that pools client assets holds the FinTech licence, while one that keeps each client’s assets on individual blockchain addresses needs no banking licence. A venue for multilateral trading of DLT securities with retail participants holds the DLT trading facility licence. Cross-border provision into Switzerland can also trigger these requirements, assessed by FINMA case by case.
| Route | Law | Who | Scope |
|---|---|---|---|
| SRO membership | Anti-Money Laundering Act | Exchanges, brokers, payment systems, custodians on individual addresses | AML supervision through one of ten FINMA-recognised SROs including VQF, PolyReg, ARIF, AOOS, SO-FIT and SRO-Treuhand Suisse |
| FinTech licence | Banking Act, Article 1b | Pooled custody of crypto-based assets; firms accepting public deposits | Deposits up to CHF 100 million, not invested, no interest, outside depositor protection, with clients informed |
| DLT trading facility | Financial Market Infrastructure Act, Articles 73a and following | Multilateral trading of DLT securities with retail access; central custody or clearing of DLT securities | Legal entity under Swiss law with registered and head office in Switzerland; audit firm review before licensing |
Trading securities for clients requires a securities firm licence under the Financial Institutions Act, and accepting deposits from more than 20 clients a banking licence.
| Requirement | Amount |
|---|---|
| FinTech licence | Minimum capital under Article 17a of the Banking Ordinance, evidenced in the application |
| DLT trading facility | Minimum capital under the Financial Market Infrastructure Ordinance with a three-year capital forecast |
| SRO membership | No FINMA capital requirement; the SRO’s own rules apply |
FINMA’s guidelines require evidence of compliance with the minimum capital requirement rather than stating the figure, which the ordinance for the chosen route sets.
| Figure | Value | Source |
|---|---|---|
| Statutory decision period | No statutory period; FINMA states that duration depends on the complexity of the project and the quality and completeness of the application | FINMA FinTech licence and DLT trading facility pages |
| Application preparation | 8 to 10 weeks | From instruction to submission, including banking in parallel |
| Our realistic timeline | 4 to 6 months after submission for a FINMA licence | The firm’s own figure, from the regulator’s published data and its own applications |
Figures published by the regulator are quoted as published and converted to months. The realistic timeline is the firm’s own, for a complete, well-prepared application.
| Item | Amount | Notes |
|---|---|---|
| FINMA licensing fee | Under the FINMA Fees and Levies Ordinance | FINMA’s pages state no amount |
| Authorisation enquiry | Normally subject to a fee | Through the EHP platform |
| SRO joining and annual fees | Set by each SRO | Vary by SRO |
| Licensing audit | Set by the audit firm | Case by case for the FinTech licence; mandatory for a DLT trading facility |
| Professional fees | Fixed, in writing | Quoted after scoping |
The routes apply to Swiss-domiciled entities and to cross-border provision into Switzerland, which FINMA assesses case by case. A Swiss firm serving the European Union holds a MiCA authorisation and one serving the United Kingdom the FCA cryptoasset authorisation; the firm obtains each.
FINMA states that incomplete or low-quality applications lengthen the process and that it may request further information, which it notes is likely for distributed ledger matters. It also states that it does not give comprehensive legal advice on business models, so the route is settled before filing.
A virtual asset firm needs accounts for client fiat funds, separated from its own, and operating accounts in the markets it serves. Banks that serve the sector review the financial crime framework first: customer due diligence, transaction monitoring, travel rule arrangements and the wallet screening tools. The firm arranges the accounts through institutions that serve licensed virtual asset firms and prepares the framework they review alongside the application. See banking and payment processing.
No. FINMA applies the Anti-Money Laundering Act and its existing licences to crypto firms: SRO membership for exchange and brokerage, the FinTech licence for pooled custody, and the DLT trading facility licence for trading venues.
An exchange or broker that keeps client assets on individual blockchain addresses needs SRO membership for AML supervision rather than a FINMA licence. Pooled custody requires the FinTech licence.
A licence under Article 1b of the Banking Act, in force since 1 January 2019, allowing public deposits of up to CHF 100 million, held without investment or interest and outside depositor protection, with clients informed.
There is no statutory period. FINMA states that duration depends on the complexity of the project and the quality and completeness of the application; the firm plans for four to six months after submission for a FINMA licence.
In Switzerland, with its registered office there; a DLT trading facility also needs its head office there. Zug and Zurich host most of the sector; the firm advises on the canton with the banking and audit relationships in mind.
A regulatory advisory firm to payment, e-money and cryptoasset companies since 2013, with more than 250 licences obtained in more than 60 countries. The firm advises on authorisation, compliance, safeguarding, banking and transactions, and builds the white-label payment and card technology its clients launch on.
A written proposal on cost, timing and requirements, the same day: speak to an expert.
This guide is general information for firms considering authorisation and is reviewed against the regulator’s published requirements. It is not legal advice; requirements and fees change, and the regulator’s current publications take precedence.
The requirements, the cost and the timing for your business, in a written proposal the same day.