 Payment Institution
Obtained Nexpay’s FCA Authorised Payment Institution licence.
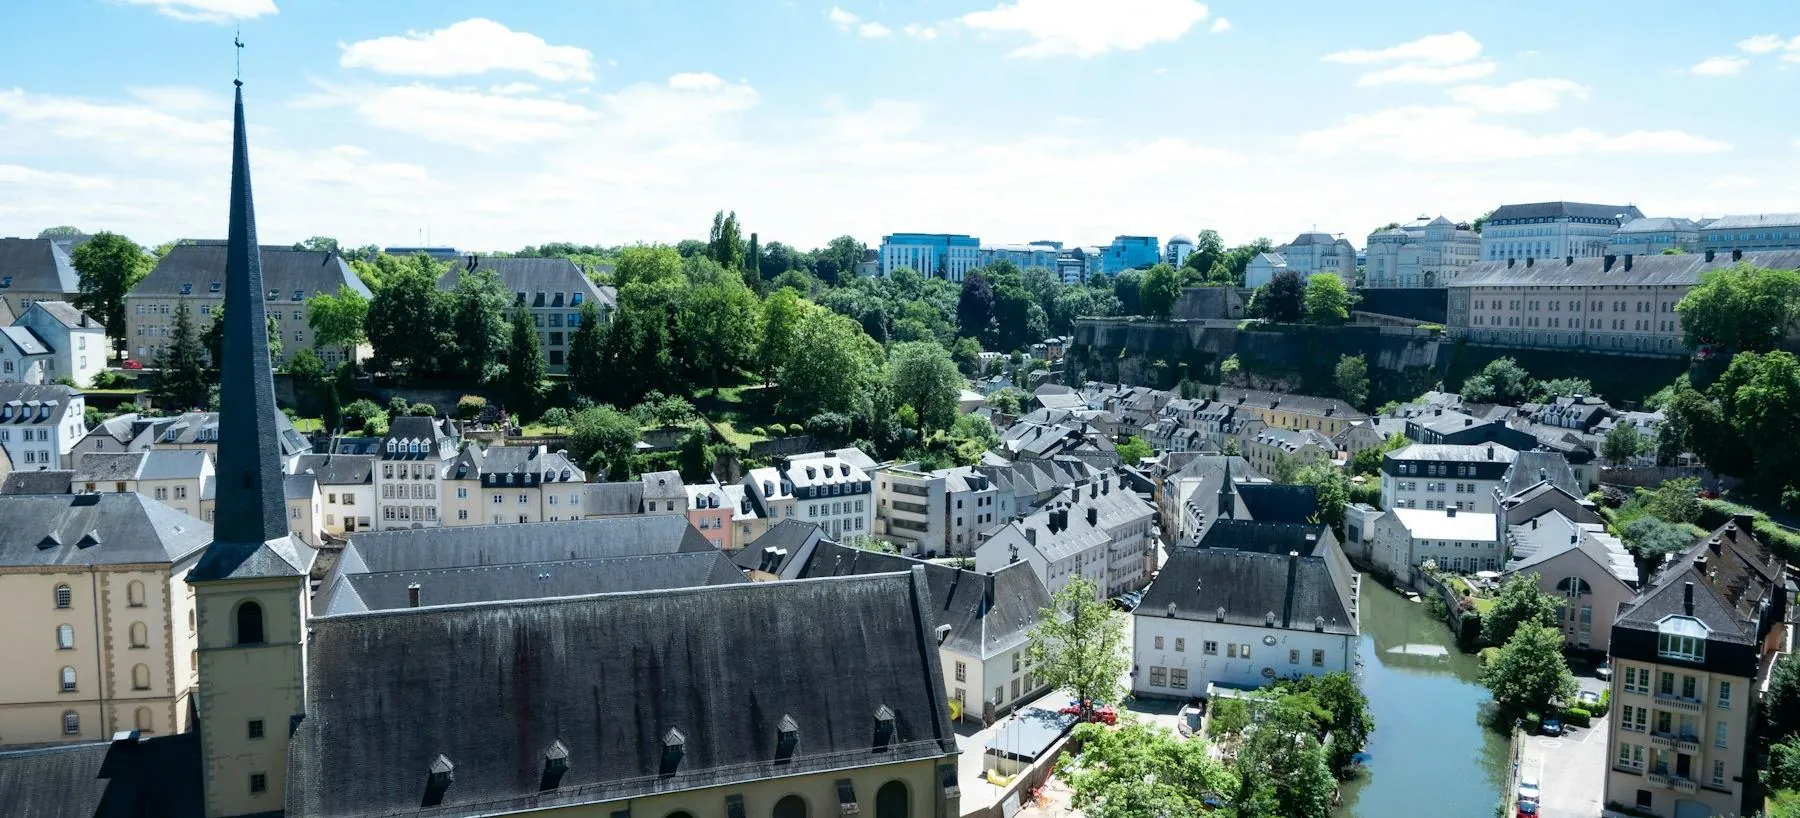
Large payment and e-money groups run their EU operations from Luxembourg, where the regulator, the banks and the professional infrastructure are built for institutional applicants.
Selected engagements from more than 250 licences obtained since 2013, for payment, e-money, cryptoasset and consumer credit firms.
 Volkswagen



 Payment Institution
Obtained Nexpay’s FCA Authorised Payment Institution licence.
 Electronic Money Institution
Obtained Dzing Finance’s FCA Authorised Electronic Money Institution licence.
Obtained Orbital’s FCA Authorised Payment Institution licence.
Our realistic timeline from submission, set against the regulator’s own published figures.
Safeguarding, operating and settlement accounts opened alongside the application, so you trade on authorisation.
Candidates introduced for directors based in Luxembourg, each assessed against the regulator’s standard.
A reply within three business hours and a written proposal the same day: the licence, the requirements, the cost and the timing.
You will need directors with senior experience in similar businesses who run the company from Luxembourg, plus supervisory board members.
One engagement and one timetable, from scoping to launch. Speak to an expert about the people, the banking and the technology for this licence.
The regulator’s requirements, capital, timing, fees and the questions firms ask, from the regulator’s own publications.
A business issuing stored value in Luxembourg or, through passporting, across the EU and EEA needs CSSF authorisation. Luxembourg hosts the EU operations of several of the largest payment and e-money groups, and its regulator, its banks and its professional infrastructure are built for institutional applicants. An EMI may provide every payment service under the same authorisation.
| Requirement | Amount |
|---|---|
| Initial capital | €350,000 |
| Ongoing own funds (Method D) | At least 2% of average outstanding e-money |
| Payment services | Method A, B or C as determined |
The law contains no small e-money regime; every issuer holds the full authorisation.
| Figure | Value | Source |
|---|---|---|
| Statutory decision period | 3 months from the application or from missing information; 12 months at most | Law of 10 November 2009 |
| Application preparation | 6 to 8 weeks | From instruction to submission, including banking in parallel |
| Our realistic timeline | 6 to 8 months after submission | The firm’s own figure, from the regulator’s published data and its own applications |
Figures published by the regulator are quoted as published and converted to months. The realistic timeline is the firm’s own, for a complete, well-prepared application.
| Item | Amount | Notes |
|---|---|---|
| Examination fee | €30,000 | Single lump sum for a new authorisation; €6,000 to extend to additional payment services |
| Annual fee | €30,000 | €40,000 where combined payment and e-money volume exceeds €1 billion; €25,000 for institutions authorised three years or less below that volume |
| Initial capital | €350,000 | Held before authorisation |
| Professional fees | Fixed, in writing | Quoted after scoping |
A Luxembourg EMI passports throughout the EU and EEA by branch, agent or distributor, or cross-border services, on notification to the CSSF.
The CSSF publishes no list of causes of delay. In the firm’s experience the causes are the same as in every EU regime: incomplete files, insufficient substance in Luxembourg, and flows of funds that are not clearly mapped.
An EMI needs a safeguarding account that satisfies the regulator’s requirements, an operating account and settlement accounts in the currencies it serves. The firm arranges each through institutions that serve regulated firms in Luxembourg and across the EU, during the application, so the firm trades on authorisation. See banking and payment processing.
Three months from the application or from the missing information, and twelve months at most, after which silence is a deemed refusal. The firm plans for six to eight months after submission.
A €30,000 examination fee on application and an annual fee of €30,000, €40,000 above €1 billion of volume, reduced to €25,000 for the first three years.
The central administration and registered office, with the people responsible for management competent to direct the business from there.
No. Every issuer holds the full authorisation.
A regulator and banking sector accustomed to institutional scale, a stable legal environment, and a position at the centre of the EU.
A regulatory advisory firm to payment, e-money and cryptoasset companies since 2013, with more than 250 licences obtained in more than 60 countries. The firm advises on authorisation, compliance, safeguarding, banking and transactions, and builds the white-label payment and card technology its clients launch on.
A written proposal on cost, timing and requirements, the same day: speak to an expert.
This guide is general information for firms considering authorisation and is reviewed against the regulator’s published requirements. It is not legal advice; requirements and fees change, and the regulator’s current publications take precedence.
The requirements, the cost and the timing for your business, in a written proposal the same day.